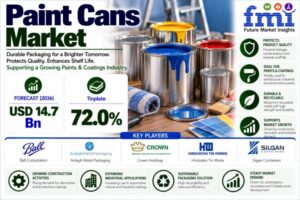

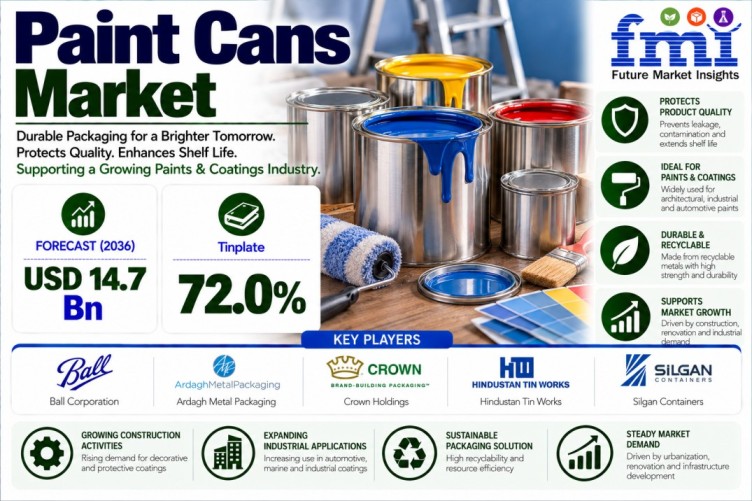
The global paint cans market is projected to increase from US$9.6 billion in 2026 to US$14.7 billion by 2036, registering a compound annual growth rate (CAGR) of 4.3% during the 2026–2036 forecast period, according to Future Market Insights (FMI). Demand is supported by decorative repainting, industrial coatings production and the continued use of rigid packaging formats that provide dependable storage, handling and transportation performance.
Paint cans remain an important packaging format for decorative paints, industrial coatings, automotive paints and protective coatings. Manufacturers continue to prioritize leakage control, closure reliability and compatibility with established filling lines when selecting packaging formats. These operating requirements are helping metal paint cans maintain a leading position despite growing interest in lightweight and alternative materials.
>> Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-gb-6677
Decorative Paints and Metal Cans Lead Market Demand
FMI estimates that decorative paints will account for 48.0% of the paint cans market by end use in 2026. Residential repainting, home improvement and light commercial renovation activities support recurring demand for packaged decorative coatings.
By format, metal paint cans are expected to hold 66.0% of market demand in 2026. Their established use across paint filling operations, stack strength and familiar handling characteristics continue to support adoption among paint producers and distributors.
Tinplate steel is projected to remain the leading material, accounting for 72.0% of the market in 2026. Its rigidity, barrier performance and compatibility with existing can-making infrastructure make it suitable for mainstream paint packaging applications.
Other notable segment characteristics include:
- Capacity: Paint cans in the 1-to-5-liter range are projected to account for 42.0% of demand in 2026.
- Closure type: Friction lids are expected to hold a 44.0% share, supported by familiar opening and resealing performance.
- Sales channel: Direct industrial supply is projected to represent 41.0% of demand, reflecting repeat purchasing and established supply relationships.
Key Growth Drivers and Industry Trends
Decorative Repainting and Construction Activity
Regular home maintenance, renovation and commercial repainting generate recurring demand for decorative paint packaging. As packaged coatings reach a wider range of retail and contractor channels, manufacturers require cans that accommodate different purchase quantities and handling conditions.
Industrial Coatings and Product Protection
Industrial coatings require packaging that supports storage, distribution and routine handling. Metal cans remain relevant where rigidity, product protection and compatibility with existing production systems are important purchasing considerations.
Lightweighting and Alternative Can Formats
Paint can manufacturers are evaluating material reduction and hybrid packaging designs to improve material efficiency. However, adoption depends on whether new formats can maintain leakage control, pallet stability, shelf durability and reseal performance. Packaging changes must also work reliably within existing filling and distribution operations.
Coating and Closure Innovation
Developments in can coatings, liners and closure systems can help manufacturers address product compatibility and packaging performance requirements. Improved surface finishes and reliable closures are particularly important for producers seeking to maintain product quality throughout storage and distribution.
Regional Opportunities: India Leads Country Growth
FMI’s country-level forecasts indicate that India will record the fastest growth, with a projected CAGR of 6.4% through 2036. Expanding housing activity, rising paint consumption and wider availability of packaged coatings are expected to support demand.
Other highlighted country forecasts include:
- China: 5.6% CAGR, supported by domestic coatings production and industrial packaging requirements.
- Brazil: 5.0% CAGR, driven by repainting demand and regional distribution activity.
- Mexico: 4.8% CAGR, supported by industrial coatings demand and cross-border manufacturing links.
- Germany: 4.2% CAGR, reflecting established industrial production and coatings requirements.
- United States: 4.0% CAGR, supported by housing maintenance, commercial repainting and industrial applications.
- Japan: 3.8% CAGR, reflecting mature coatings demand and replacement-led packaging purchases.
North America is projected to account for 30.0% of the global market in 2026. Established retail paint distribution, industrial maintenance and familiar metal packaging systems support the region’s importance.
For suppliers, India’s growth outlook creates opportunities to strengthen local distribution and manufacturing partnerships. Meanwhile, mature markets such as the United States, Germany and Japan offer opportunities centered on product consistency, specification improvements and reliable supply.
Competitive Landscape: Top Players in the Paint Cans Market
The global paint cans market includes established metal packaging manufacturers and suppliers serving decorative and industrial coatings producers. Competition is influenced by manufacturing capabilities, material selection, closure performance, product quality and regional supply networks.
Companies identified in FMI’s report include:
- Ball Corporation
- Ardagh Metal Packaging
- Crown Holdings
- Hindustan Tin Works
- Silgan Containers
- Mauser Packaging Solutions
- Sonoco Products Company
These companies participate in the broader rigid packaging and metal container ecosystem. Their market positioning is shaped by their ability to meet customer specifications, maintain production consistency and support dependable delivery.
The report also identifies developments relevant to the competitive environment. In July 2024, AkzoNobel launched its first BPA-free coating production line in Asia for can packaging. In February 2025, Ardagh Metal Packaging reported 3% growth in global volumes for 2024. In November 2024, Ball Corporation acquired Alucan to expand its impact-extruded aluminum packaging business in Europe.
Access Detailed Market Insights: https://www.futuremarketinsights.com/reports/paint-cans-market
Strategic Priorities for Paint Can Manufacturers
The market outlook points to several business priorities. Manufacturers can focus on improving tinplate steel packaging performance while evaluating lightweight and hybrid alternatives through practical filling-line and distribution trials.
Investments in closure reliability, coating technology and material efficiency may help suppliers differentiate their offerings. Companies targeting high-growth markets can also assess regional partnerships and distribution capabilities, particularly in India and China.
For paint producers, packaging decisions should consider more than material costs. Leakage prevention, stacking performance, shelf durability and resealing reliability remain essential factors in selecting paint can suppliers.