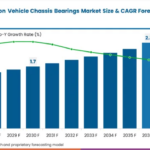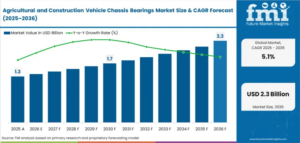

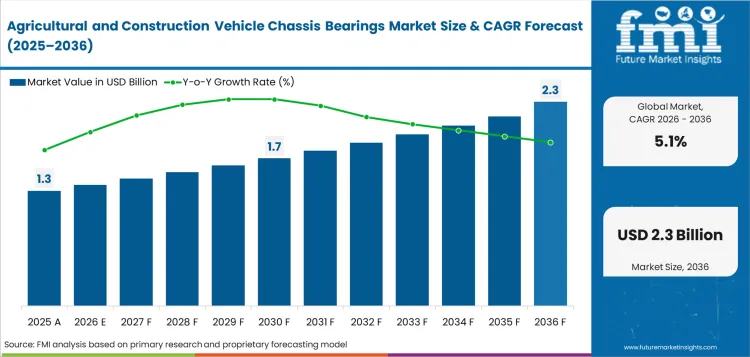
The global agricultural and construction vehicle chassis bearings market was valued at USD 1.3 billion in 2025 and is set to reach USD 1.4 billion by 2026-end. Expanding at a 5.1% CAGR from 2026 through 2036, global market revenue is projected to reach USD 2.3 billion by 2036, creating an absolute incremental opportunity of USD 0.9 billion over the ten-year forecast period. Driven by heavy wheel-end loads across off-road equipment, harsher operating environments, and expanding dealer maintenance networks, off-highway original equipment manufacturers (OEMs) and aftermarket suppliers are increasingly prioritizing high-performance, sealed chassis bearing solutions.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsights.com/reports/sample/rep-gb-33172
Key Market Highlights at a Glance
• 2025 Baseline Market Valuation: USD 1.3 billion
• 2026 Estimated Market Value: USD 1.4 billion
• 2036 Forecasted Market Size: USD 2.3 billion
• Ten-Year Compound Annual Growth Rate (CAGR 2026-2036): 5.1%
• Absolute Incremental Revenue Opportunity (2026-2036): USD 0.9 billion
• Leading Bearing Type Segment (2026 Share): Tapered roller bearings, capturing a 39.0% market share
• Leading Vehicle Type Segment (2026 Share): Construction vehicles, commanding a 54.0% market share
• Leading Application Segment (2026 Share): Wheel hub assemblies, holding a 36.0% market share
• Leading Material Segment (2026 Share): High carbon chromium steel, representing a 63.0% market share
• Leading Sales Channel Segment (2026 Share): OEM fitment, accounting for a 58.0% market share
• Fastest-Growing Regional Demand Centers: India expanding at a 6.2% CAGR and China expanding at a 5.5% CAGR
• Report Page Count: 250 Pages
Why Is the Agricultural and Construction Vehicle Chassis Bearings Market Growing?
Demand for heavy-duty chassis bearings is escalating as farm and construction machinery platforms undergo severe duty cycles in demanding off-road conditions:
• Heavy Wheel-End Loads: Off-highway machinery is experiencing higher axle stress during intensive field and jobsite operations, requiring robust bearings to handle extreme radial and thrust forces.
• Contamination Risk and Low-Maintenance Design: Exposure to slurry, mud, and water increases field failure rates, pushing OEMs toward advanced sealed bearing units that reduce manual relubrication cycles.
• Expanding Aftermarket Service Kits: Authorized dealers and service shops are stocking complete replacement hub and pivot kits to accelerate machinery repair and minimize operational downtime.
“Chassis bearings are becoming reliability filters for farm and construction vehicle OEMs,” stated Nikhil Kaitwade, Principal Consultant for Automotive at FMI. “Wheel hubs and axle pivots drive demand. Bearing steel raises cost. Seal testing and local application engineering protect approvals while counterfeit service parts threaten replacement agreements.”
Which Segments Lead the Agricultural and Construction Vehicle Chassis Bearings Market?
Bearing Type and Material Analysis
Tapered roller bearings are projected to dominate bearing type sales, capturing 39.0% of bearing type revenue in 2026. Tapered designs provide essential radial control and thrust control at wheel-end positions under heavy tilting loads. In terms of construction materials, high carbon chromium steel leads material demand, holding 63.0% of material share in 2026 due to its superior fatigue strength and shock-load resistance following controlled heat treatment.
• Tapered Roller Bearings: Forecast to lead bearing types with a 39.0% market share in 2026 owing to simultaneous radial and thrust load management.
• High Carbon Chromium Steel: Projected to command 63.0% of material demand in 2026 due to extreme fatigue resistance under repeated shock loads.
• Alternative Types and Materials: Spherical roller bearings, ball bearings, plain bearings, stainless steel, polymer composites, and bronze alloys represent the remaining market shares.
Vehicle Type, Application, and Sales Channel Breakdown
Construction vehicles represent the primary equipment segment, expected to account for 54.0% of the vehicle type segment in 2026 due to massive axle strain in loaders, excavators, and earthmoving platforms. Wheel hub assemblies serve as the leading application, forecast to hold a 36.0% application share in 2026 as constant mud exposure and side-load stress make wheel ends a frequent service item. Regarding distribution, OEM fitment commands the market with an estimated 58.0% sales channel share in 2026, as bearing specifications are established during vehicle engineering.
• Construction Vehicles: Expected to capture 54.0% of vehicle type demand in 2026 driven by heavy-duty earthmoving applications.
• Wheel Hub Assemblies: Forecast to account for 36.0% application share in 2026 due to frequent replacement and high load exposure.
• OEM Fitment Channel: Estimated to hold 58.0% sales channel share in 2026 owing to rigorous platform validation requirements.